A six-year-old finds a dollar in a coat pocket and stops cold. They stare at it like it is a map to a secret treasure.
Then comes the question every parent eventually hears:
“What can I buy with this?”
That moment matters more than most parents realize.
The child is not asking for a lesson on compound interest or investment portfolios. They are asking about money in a way that suddenly feels real to them.
The answer you give, or perhaps more importantly, the questions you ask in return, can become one of the first building blocks of financial literacy for kids.
Money lessons do not need to wait until children receive their first paycheck. They can begin much earlier, during small everyday moments when the amounts are tiny and the consequences are safe.
Watching you compare prices at the grocery store, deciding whether to spend birthday money, choosing between a toy and a treat, or saving toward something special are not trivial experiences. They are opportunities for children to begin learning how money works.
Children develop money habits much the same way they develop many other life skills: through exposure, repetition, practice, and experience.
If the first time a child manages money independently is when they are 16 and working a summer job, mistakes can suddenly become much more expensive.
A six-year-old who spends a dollar on a toy that breaks by dinner has learned something for a dollar. A teenager making the same type of impulsive decision might lose considerably more.
The goal is not to prevent children from ever making a poor money decision.
It is to give them opportunities to practice while the stakes are still small.
Start Financial Literacy for Kids With Needs and Wants
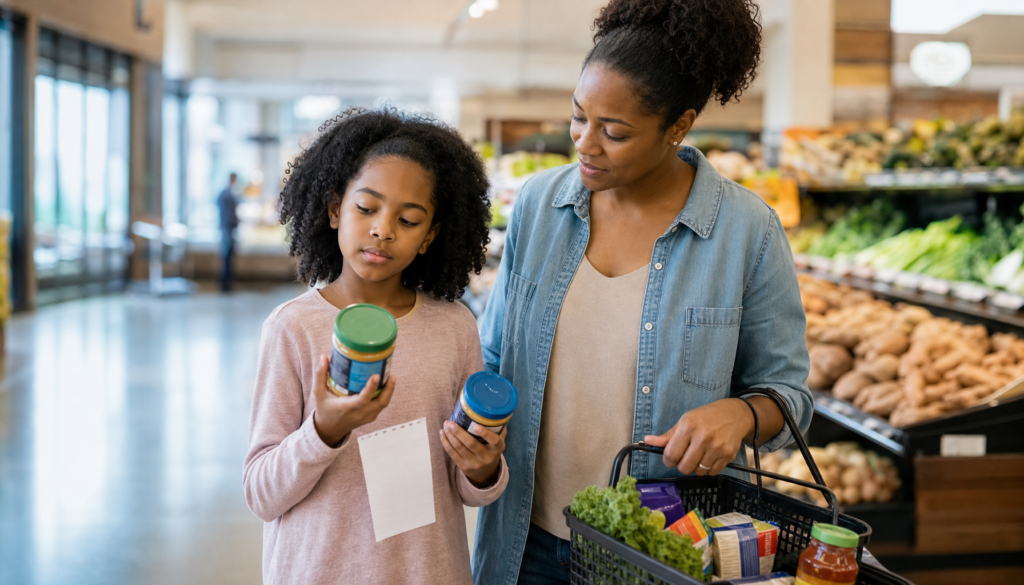
The grocery cart is half full, and your seven-year-old is holding a bright blue box of dinosaur-shaped cookies.
You already said no to the sugary cereal and the toy near the checkout. Now the negotiating begins.
Instead of immediately saying no again, try asking:
“Is that something you need or something you want?”
That simple question gives your child a framework they can eventually use without you.
A need is something necessary for everyday life, such as food, water, shelter, and appropriate clothing. A want is something we would enjoy having but can live without.
The important lesson is not that wants are bad.
Wants are part of life. They also give children a reason to save, plan, compare alternatives, and decide what matters most to them.
When your child asks for something, you can occasionally respond with questions such as:
- Would you be okay if we did not buy this today?
- Is there another version that costs less?
- If you spend your money on this, what will you have left?
- What else are you saving for?
- Is this something you need or something you want?
These conversations can happen almost anywhere.
At the grocery store, children can identify necessities and optional treats. When planning a weekend, they can compare activities that cost money with free alternatives. While shopping for school supplies, they can consider whether the more expensive version actually provides something they need.
The objective is not to turn every shopping trip into a financial lesson.
Instead, use ordinary opportunities to help children recognize that spending involves choices.
Once they understand needs and wants, those choices become much more meaningful when children have a little money of their own to manage.
Give Kids a Little Money and Real Choices
Hand a child five dollars at a school book fair and watch what happens.
Suddenly every decision matters.
They compare books. They inspect novelty pencils. They reconsider the pizza-shaped eraser. They calculate what will be left if they buy something.
Something changes when children are deciding what to do with money they consider their own.
Advice such as “save your money” becomes much more meaningful when spending the money means they cannot use it for something else.
A child who has never controlled even a small amount of money has difficulty understanding what saving actually feels like.
A child with three dollars who wants two different things quickly discovers an important financial principle:
Money is limited, so choices have consequences.
That is why the amount matters less than the experience.
A small allowance, birthday money, or a few dollars provided for a particular outing can create a safe environment for practice.
Children will sometimes make choices you would not make.
That is okay.
If your child spends three dollars on a toy you suspect will lose its appeal tomorrow, consider whether this is a situation where you can allow the decision to stand.
The goal is not to raise children who make perfect spending decisions.
It is to raise children who learn to think about their decisions.
Connect Earning, Saving, and Goals
Once children understand that money is limited, they can begin learning another important concept: money can be earned.
Families approach allowances and household responsibilities differently, and there is no single system that works for everyone.
One approach is to distinguish between responsibilities children perform because they are members of the household and additional age-appropriate jobs they can complete to earn money.
A younger child might match socks, help organize something, or complete another simple task. An older child might wash a car, rake leaves, help with yard work, or take responsibility for a larger project.
The larger lesson is that money is connected to effort and value.
Once children have an opportunity to earn money, saving becomes much more meaningful.
Help your child choose a simple savings goal.
Perhaps they want a particular toy, book, game, craft set, or special outing.
Write down the price and determine how much they already have.
Then ask:
“How much more do you need?”
That turns saving from an abstract virtue into a concrete plan.
If your child earns money periodically, you can also help them estimate how long reaching the goal might take.
Tracking progress does not need to feel like homework.
A simple chart on the refrigerator can work. Younger children may enjoy coloring sections of a savings tracker. A clear savings jar allows them to physically see their money accumulate.
The method matters less than making progress visible.
Waiting is difficult for children. That is precisely why saving provides such valuable practice.
Every time a child decides not to spend money immediately because something else matters more, they are practicing patience, planning, and delayed gratification.
Turn Shopping Into a Money Classroom
The grocery store offers one of the easiest places to practice financial literacy.
There are dozens of similar products, different prices, different quantities, tempting extras, and a limited amount of money available to spend.
Invite your child into some of those decisions.
You might point to two similar products and ask:
“Which one costs less?”
For an older child, take the lesson one step further.
“Do you think the more expensive one is worth the difference?”
Now you are teaching something more sophisticated than finding the lowest price.
You are teaching value.
Children can also begin learning about tradeoffs.
Suppose one item costs two dollars more than another. Ask what else those two dollars could purchase.
Money now represents possibilities rather than simply numbers printed on price tags.
Another activity is giving your child a small budget for something specific.
For example:
“You have five dollars to choose a snack for the week.”
Now the child has to compare prices, consider quantities, think about preferences, and remain within a limit.
They may discover that choosing one item means giving up another.
That is budgeting in its simplest form.
Let Small Money Mistakes Become Lessons
Children will occasionally make poor financial decisions.
That is not evidence that the lessons are failing.
It is part of the learning process.
Perhaps your child spends all their money and regrets it the next day. Maybe they buy something that looked exciting in the store but quickly becomes boring. Perhaps they refuse to save toward a larger goal and later wish they had.
When the stakes are small and there is no meaningful harm involved, resist automatically rescuing them.
Instead, ask questions.
“Are you happy with what you bought?”
“Would you make the same choice again?”
“What might you do differently next time?”
Those questions transform regret into reflection.
Avoid turning the conversation into “I told you so.”
If children believe every mistake will result in a lecture, they may become more interested in hiding their mistakes than learning from them.
A better goal is to help them examine what happened and make a better plan for next time.
The lesson is not that making mistakes with money is acceptable forever.
The lesson is that mistakes can provide information that improves the next decision.
Introduce Simple Budgeting
Once children have experience earning, saving, and spending, they can begin learning a basic budgeting system.
One familiar approach uses three containers labeled:
Save
Spend
Share
Whenever children receive money, they decide how much should go into each category.
Families can determine the amounts or proportions that make sense for them.
The Spend category provides money children can use for everyday wants.
The Save category helps fund larger goals.
The Share category introduces another dimension of money: using it to help someone else, contribute to a cause, or purchase a gift.
Clear containers can be especially useful for younger children because money becomes visible.
They can see one container growing while another becomes smaller after a purchase.
Older children can eventually move from jars to a notebook, worksheet, spreadsheet, or age-appropriate digital system.
The tool can change as the child grows.
The underlying habit remains the same:
Decide what you want your money to accomplish before spending it.
Make Money Conversations Part of Everyday Life
Financial education does not require a formal family meeting every time money comes up.
Some of the most useful lessons happen during ordinary conversations.
You might explain why you are comparing two products.
You might tell your child:
“This one costs more, but we use it frequently, so I think it is worth paying a little extra.”
Or:
“We could buy that today, but we are saving for our trip, so I would rather keep the money for that.”
These small comments allow children to hear the thinking behind financial decisions.
They begin to understand that adults also make tradeoffs.
We cannot purchase everything simply because we can afford an individual item.
We prioritize.
We plan.
We postpone some purchases.
We occasionally change our minds.
We sometimes make mistakes.
When children see money treated as a practical tool rather than a mysterious adult subject, they have more opportunities to develop healthy attitudes toward it.
The Goal Is Thoughtful Money Decisions
Teaching financial literacy for kids is not about creating miniature financial experts.
A nine-year-old does not need to understand every financial concept they will encounter as an adult.
They need a foundation.
Can they distinguish between something they need and something they want?
Can they understand that spending money on one thing means it cannot be spent on something else?
Can they save toward a goal?
Can they compare alternatives before purchasing?
Can they work within a simple budget?
Can they reflect on a decision that did not work out as expected?
Those are substantial skills.
A structured resource can provide additional practice when children are ready to go further. Activities involving needs and wants, saving and spending, earning, budgeting, shopping decisions, purchase planning, and financial responsibility can reinforce the same lessons children encounter in everyday life.
But the most important classroom is already around them.
It is the grocery aisle.
The birthday money.
The school book fair.
The savings jar.
The item they decide not to buy today because they want something else more tomorrow.
Every small money decision gives children another opportunity to practice.
The goal is not to make every decision for them.
It is to gradually prepare them to make thoughtful decisions for themselves.